Personal Finance
New Presumptive Tax Rules: 1% of Turnover for Small Firms
Lagos, 4 November 2026 · Gopexly Desk · Published 4 November 2026 at 17:00 · Updated 9 November 2026 at 11:10 · 5 min read
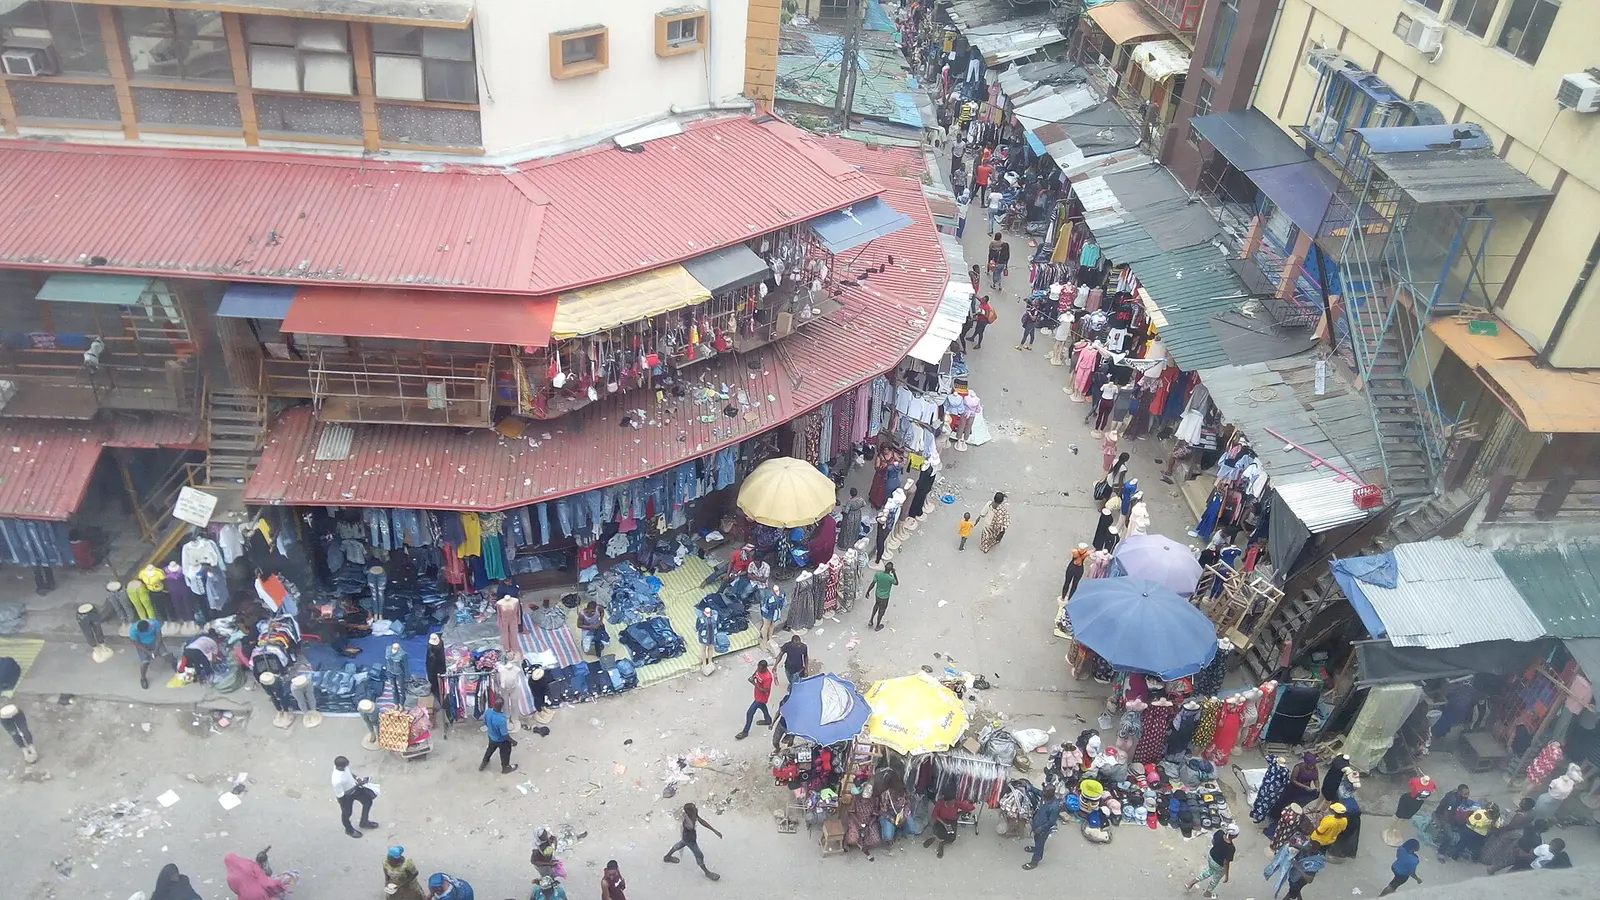

Nigeria's Presumptive Tax Regulations, 2026 allow tax authorities to charge informal businesses 1% of their actual or estimated turnover where proper records are missing, and to estimate that turnover using factors such as the owner's lifestyle, assets and bank transactions. Businesses with turnover of ₦12 million a year or less are exempt, as are listed petty trades. The rules took effect on 1 January 2026 but drew fresh attention after Punch reported on them on 1 November.
What the regulations are
The regulations were made under Section 29 of the Nigeria Tax Act, 2025, by the former Minister of Finance, Wale Edun, who left office in April 2026 according to Udo Udoma & Belo-Osagie, on the advice of the Joint Revenue Board. Punch says they were issued as Statutory Instrument No. 24 of 2026 and published in the Official Gazette dated 13 May 2026. Law firm Udo Udoma & Belo-Osagie, writing on Legal 500, gives the gazette as No. 85 of 13 May 2026. Both say the rules apply from 1 January 2026.
Who is covered
The regime applies to two groups, according to the regulations as summarised by Punch, KPMG and Udo Udoma & Belo-Osagie:
- people whose businesses are not organised to keep proper records for tax; and
- people whose income cannot be worked out with reasonable accuracy, including where information has been deliberately withheld, hidden or misstated.
If a covered person has no Tax Identification Number, the tax authority can register them and assign one.
How the tax is worked out
- Rate: 1% of actual or estimated annual turnover.
- Best-of-judgement estimates: where information is missing, Regulation 10(2) lets the tax authority consider "the nature of business, lifestyle of the taxpayer, assets, location, association or community intelligence, and the volume of electronic and cash transaction", Punch reported.
- Daily sales: where only daily turnover can be estimated, it is multiplied by the number of working days, capped at 300 a year.
Punch gave two examples. A business with ₦20 million turnover would pay ₦200,000. A business estimated at ₦50,000 a day for 300 days has turnover of ₦15 million and would pay ₦150,000.
Because the tax is on turnover, not profit, it can be heavy for low-margin traders. As an illustration on our calculation, a trader earning a 5% margin on ₦20 million turnover makes ₦1 million in profit, and ₦200,000 of tax is 20% of that. KPMG said informal businesses above the threshold "may experience an increase in their tax obligations" compared with self-assessment.
Who is exempt
- Nano businesses with annual turnover of ₦12 million or less. Udo Udoma & Belo-Osagie notes that ₦12 million is about ₦40,000 a day over 300 working days.
- Listed petty trades in Schedule 1, including akara, roasted yam and plantain sellers, groundnut sellers, mobile barbers, tailors using manual machines, local cobblers, newspaper vendors, wheelbarrow pushers, roadside car washers, phone-charging operators, sachet water hawkers, recharge card sellers and small-scale garri processors.
- People already exempt from income tax under Section 162 of the Nigeria Tax Act.
Exempt people can get a free tax exemption certificate or sticker from the tax authority, valid for one year and renewable.
A 2% tax on some asset sales
The regulations also set a 2% presumptive tax on the sale price, not the gain, where an individual's disposal produces a chargeable gain under the Act. This covers land, buildings, movable assets, shares and intangible property. It must be paid within 30 days of the deal closing or the money being received, whichever is earlier. KPMG notes that transactions exempt from capital gains tax under the Act stay exempt.
Paying, opting out and objecting
- Electronic payment only: USSD, POS, bank transfer, mobile apps or licensed fintech platforms. Cash collection and roadblock collection are banned, Udo Udoma & Belo-Osagie said.
- Opting out: a taxpayer can leave the regime and file normal self-assessment returns by telling the tax authority before the filing deadline.
- Objections: a taxpayer can object in writing within 30 days of an assessment, then go to the Office of the Tax Ombud or the Tax Appeal Tribunal.
Where sources differ
- Who counts as a nano business. Punch quotes Regulation 6(2) as excluding anyone whose turnover does not exceed ₦12 million. KPMG and Udo Udoma & Belo-Osagie describe the exemption as also requiring no fixed premises and no formal employees, for sole proprietors or household businesses. Small business owners with a shop or staff should check the full text.
- Gazette details. Punch cites Statutory Instrument No. 24 of 2026; Udo Udoma & Belo-Osagie cites Official Gazette No. 85. These may be two references to the same publication.
What this means for you
- Keep records. Bookkeeping is the simplest way to be taxed on what you really earn rather than on an estimate. KPMG says the rules may push businesses to keep proper accounts.
- Your bank and POS history matters. The volume of electronic and cash transactions is one of the listed factors in an estimate.
- Investors selling assets informally should note the 2% rule. If you sell land or shares outside a formal filing process, ask a tax adviser how this applies.
This is for information only and is not investment advice.
FAQ
What is presumptive tax in Nigeria?
It is a simplified income tax for people and businesses without proper records. Under the 2026 regulations, it is charged at 1% of actual or estimated turnover.
Who is exempt from presumptive tax?
Nano businesses with turnover of ₦12 million a year or less, listed petty trades such as sachet water hawkers and mobile barbers, and people exempt under Section 162 of the Nigeria Tax Act.
Can the tax office really use my lifestyle to estimate my income?
Yes, where adequate information is missing. Lifestyle, assets, location, community intelligence and transaction volumes are among the listed factors. You can object within 30 days.
Sources
- Punch, "New tax rule authorises lifestyle audit to detect hidden income" (1 Nov 2026)
- Udo Udoma & Belo-Osagie via Legal 500, "Tax Reform: Key Provisions Of The Nigerian Presumptive Tax Regulations 2026"
- KPMG Nigeria, "Nigeria's Presumptive Tax Regulations, 2026: Key highlights and practical implications for taxpayers" (7 Jul 2026)
This note is for education. It is not a recommendation to buy or sell any share.
Tags: Tax, Small Business, Nigeria Tax Act, Informal Sector, Capital Gains