Banking
FCMB 9M 2026 Profit Doubles to N272.8bn on Cheaper Funds
Lagos, 21 November 2026 · Gopexly Desk · Published 21 November 2026 at 06:00 · Updated 21 November 2026 at 08:41 · 6 min read
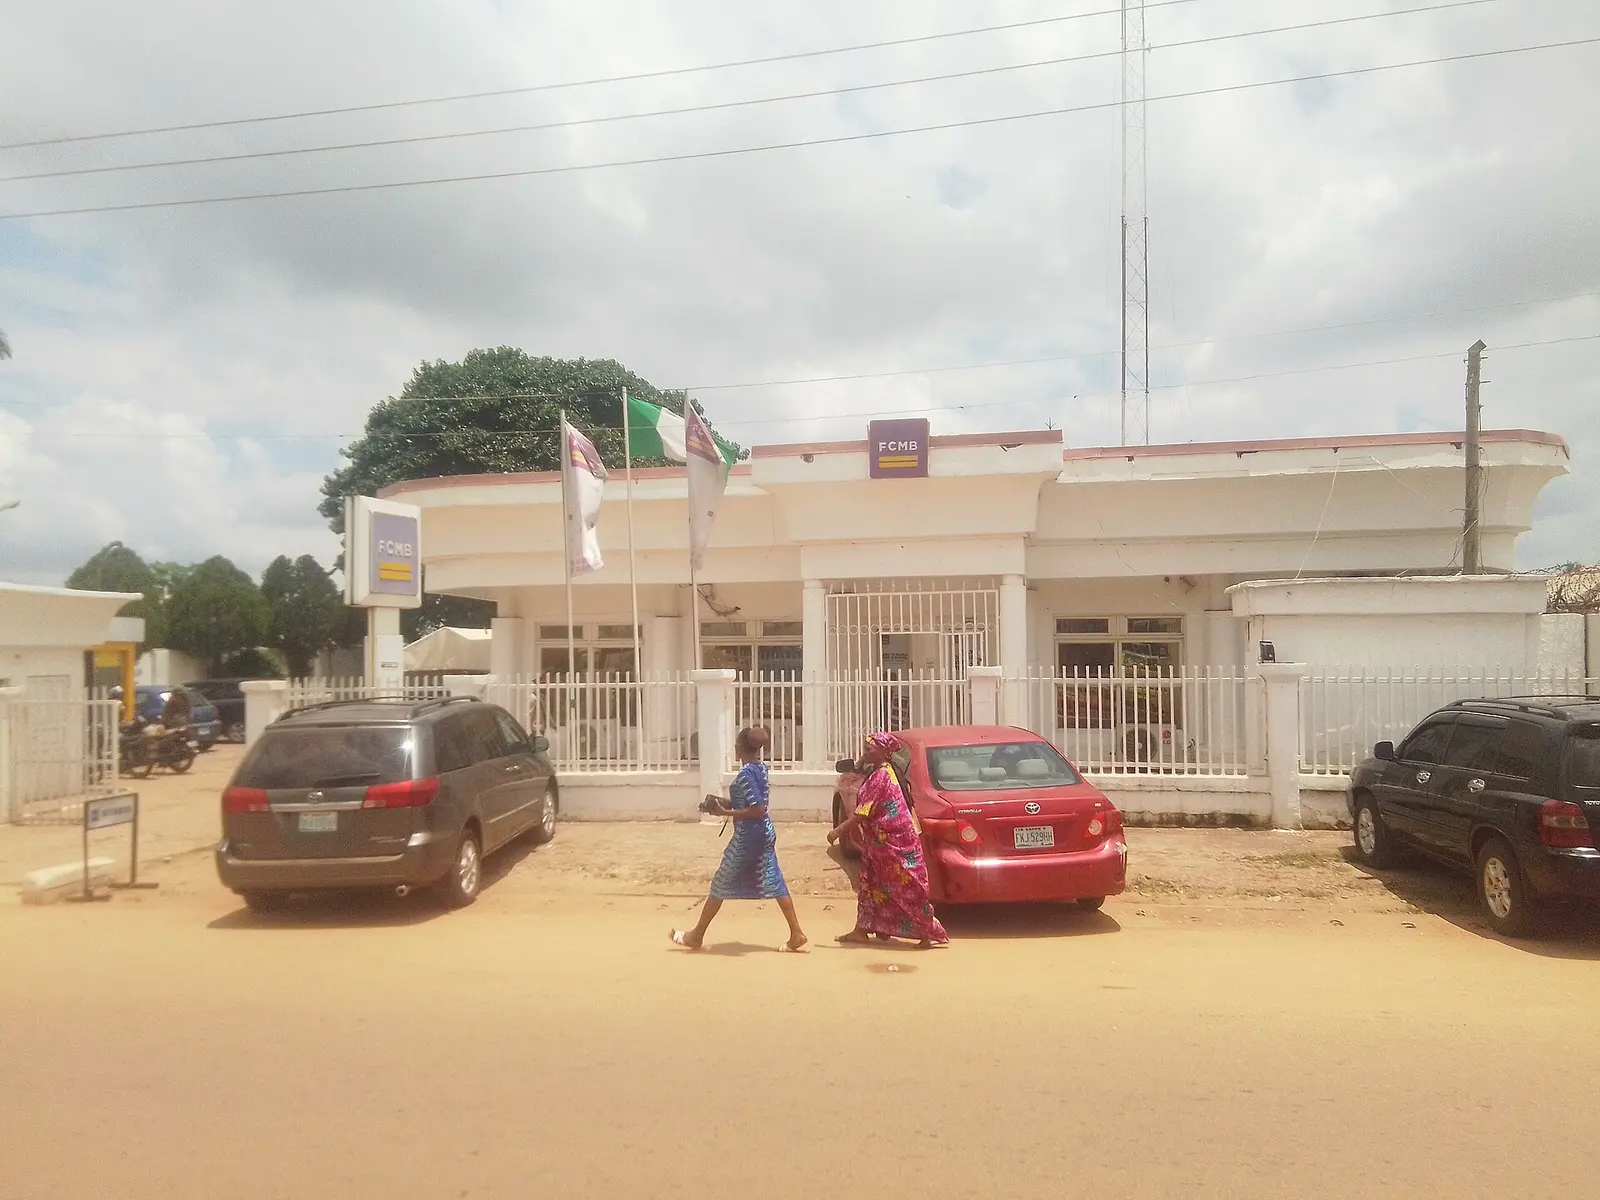

 FCMB Group Plc more than doubled its pre-tax profit in the first nine months of 2026. Profit before tax rose 102.8% to N272.77 billion in the nine months to 30 September, up from N134.50 billion a year earlier, according to the group's unaudited results released on Friday, 20 November 2026, and reported by Nairametrics and Punch.
Gross earnings crossed N1 trillion for the period, and profit after tax rose 85.7% to N232.91 billion. Lower funding costs and a bigger share of cheap deposits were the main drivers. Bad loans, however, rose at the group's Nigerian bank.
The key numbers
| Item | 9M 2026 | 9M 2025 | Change |
|---|---|---|---|
| Gross earnings | N1.00 trillion | N828.13 billion | +21.0% |
| Net interest income | N534.18 billion | N350.83 billion | +52.3% |
| Net fee and commission income | N81.91 billion | N56.19 billion | +45.8% |
| Operating expenses | N268.9 billion | N239 billion | +12.5% |
| Net impairment losses | N76.81 billion | N57.12 billion | +34.5% |
| Pre-tax profit | N272.77 billion | N134.50 billion | +102.8% |
| Profit after tax | N232.91 billion | N125.45 billion | +85.7% |
Source: FCMB Group results via Nairametrics and Punch. The impairment change is our calculation.
Third quarter beat the group's own forecast
In the third quarter alone, pre-tax profit rose 108.5% to N115.47 billion, from N55.37 billion in the same quarter of 2025. Nairametrics said this beat the group's own forecast of N98.16 billion by 17.63%, or N17.31 billion.
A key help in the quarter was a N9.12 billion net impairment write-back, meaning the bank released money it had set aside for bad loans. In the third quarter of 2025, it had booked an impairment charge of N20.90 billion.
Why profit jumped
Cheaper money. Interest income rose 23.4% to N906.03 billion as earning assets grew 10.7% to N5.43 trillion. At the same time, interest expense fell 3.0% to N371.85 billion. That combination lifted net interest income by 52.3%.
The fall in funding costs came from cheaper deposits. Current and savings account balances, which usually pay little or no interest, rose 24.4% to N3.60 trillion from N2.89 trillion in December 2025. These low-cost deposits now make up 76% of the total, up from 65.4%. As a result, the net interest margin improved to 12.3% from 10.1%.
Fees and digital business. Net fee and commission income rose 45.8%. FCMB's digital businesses, which cover payments, lending and wealth management, earned N142.5 billion, up 25.4% from N113.6 billion. They contributed 14.2% of gross earnings.
Costs grew more slowly than income. Operating expenses rose 12.5%, far slower than income. The cost-to-income ratio improved to 43.5% from 55.5%. Staff costs rose to N88.00 billion from N71.87 billion.
Where the profit came from
The banking group earned a pre-tax profit of N216.9 billion, up 94% and equal to 80% of the group total. The non-banking businesses and holding company contributed N55.9 billion, up 147%. Punch reported that assets under management rose 23% to N2.1 trillion from N1.7 trillion in December 2025.
The weak spots
Not everything improved:
- Bad loans rose. The Nigerian bank's non-performing loan ratio rose to 6.4% from 4.7% in June 2026. Management linked this to a 13% cut in the loan book during the third quarter and to new loans classified as Stage 3, the category for loans in default.
- Higher impairments for the year. Net impairment losses for nine months rose to N76.81 billion, which management tied to a clean-up of Stage 2 loans in the second quarter.
- Fewer loans. Loans and advances fell 8.3% to N2.17 trillion, as large corporate customers repaid loans. Management said digital retail and SME lending grew by more than 20% to N315 billion, but that was not enough to offset the repayments. Investment securities rose to N2.49 trillion from N2.04 trillion.
Balance sheet and capital
Total assets rose 9.7% to N8.37 trillion. Customer deposits grew 7.1% to N4.73 trillion. Total equity jumped 47.8% to N1.24 trillion, helped by retained profits and a capital injection of about N227 billion in the first quarter of 2026, part of the bank recapitalisation exercise. The capital adequacy ratio stood at 24.6% at the end of September.
What management expects
Group Chief Executive Ladi Balogun said the results reflected "the dedication of our people to building a more efficient engine that can scale with stronger unit economics."
He said he expects earnings momentum to continue in the fourth quarter. Operating costs should be lower because the full 2026 AMCON levy has already been charged in the nine-month results, and digital lending and payments usually pick up at the end of the year. With nine-month return on equity at about 30%, he said full-year return on equity should be "materially above" the earlier guidance of 25%.
Where the sources differ
The two reports describe earnings per share differently. Nairametrics put it at N4.59, up 22.7% from N3.74 in the same period of 2025. Punch described N4.59 as an annualised figure, up 15% from N3.99 for full-year 2025, and noted that the share base is now larger after the capital raise. That larger share count is why earnings per share grew much more slowly than profit. Punch also put annualised return on equity at 30.1%, up from 22.4%, and return on assets at 3.9%, up from 2.3%.
The two outlets also rounded some figures differently, such as N9 billion against N9.12 billion for the third-quarter write-back. We used the more precise figures.
How the stock traded
FCMB shares closed at N10.95 on Friday, up 0.5% from N10.90, Nairametrics reported. The stock is down 9.13% from N12.05 at the start of 2026. FCMB was also among the three most traded stocks by volume on the NGX this week, according to the exchange's weekly report.
What it means for you
- Check where the profit comes from: Much of the gain came from cheaper deposits and lower funding costs, which can change if interest rates move.
- Watch asset quality: A rising bad-loan ratio is worth tracking in the full-year results.
- Know the share count: After a capital raise, profit can grow much faster than earnings per share, which is what matters to each shareholder.
FAQs
How much profit did FCMB make in 9M 2026? FCMB Group made a pre-tax profit of N272.77 billion and a profit after tax of N232.91 billion in the nine months to 30 September 2026.
Why did FCMB's profit rise so much? Net interest income rose 52.3% as interest expense fell and cheap current and savings deposits grew. Fees rose 45.8% and costs grew more slowly than income.
What is FCMB's share price? FCMB closed at N10.95 on 20 November 2026, up 0.5% on the day but down 9.13% since the start of the year.
Sources
- Nairametrics, "FCMB's 9M 2026 pre-tax profit jumps 103% to N272.8 billion, beats Q3 forecast" (20 Nov 2026)
- Punch, "FCMB Group's PBT doubles to N272.8bn in nine months" (21 Nov 2026)
- NGX weekly market report for 20 November 2026 (via Mondo Visione)
Cover photo: FCMB branch, Sabon Tasha, Kaduna. Babe, Ishaku / Wikimedia Commons, CC BY 4.0.
This is for information only and is not investment advice.
This note is for education. It is not a recommendation to buy or sell any share.
Tags: FCMB, Bank Results, Earnings, 9M 2026, Nigerian Banks, NGX